Kevin Bemel ·
Forget Estate Planning
It’s Too Late by Then
About the source date and illustrations
The date is transcribed from Posts – Sunday 2023. The original publication date has not been independently verified. Historical figures, links, and event announcements are preserved as written.
Some illustrations from the source document are not reproduced here. Original image credits are shown for the BLS material retained in this article.
The cover photograph is illustrative. Photo: Picas Joe on Pexels · Pexels License.
4 minutes to read.
If you wait until you have substantial assets to do estate and financial planning, you’ll probably be too late to secure your economic future. Before we get into why, let’s look at the job market.
Job Market
The number of unemployed people per job opening remains lower than it has been for at least 15 years, with there being more positions available than people looking for work.
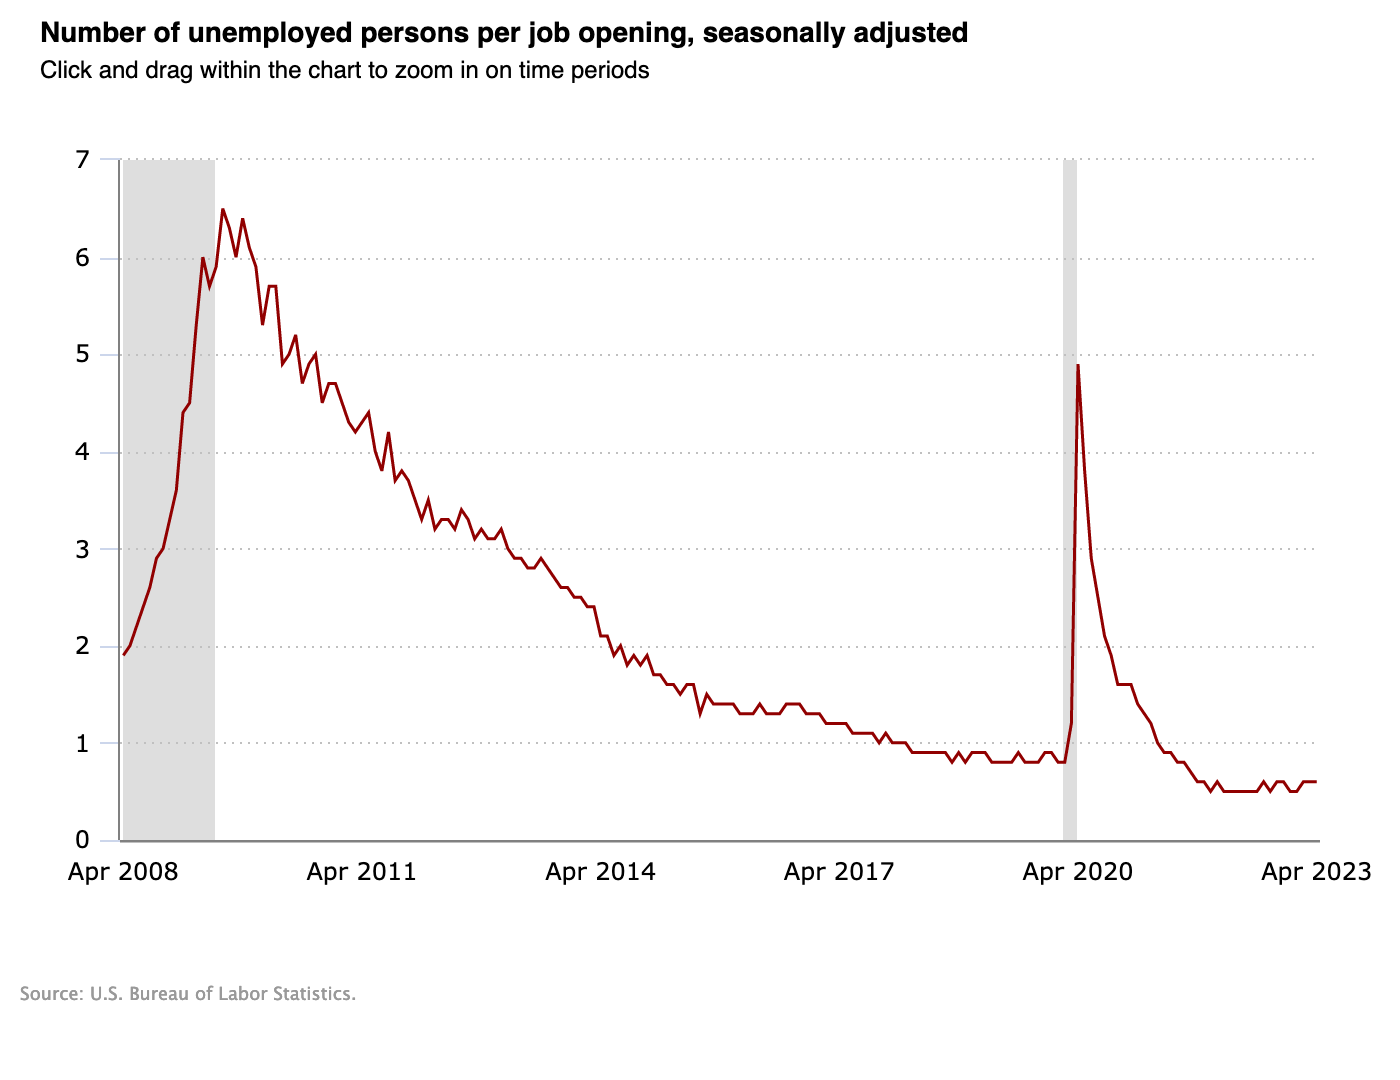
This isn’t the full picture. The unemployment rate only counts people who are actively looking for work. Consider, though, that the labor force participation rate as of April 2023 was 62.6%, which is almost 1% below the pre-pandemic February 2020 rates of 63.3%. Put another way, there are 1.17 million fewer people participating in the labor force now than before COVID. Were these people looking for work, there would be 20% more job seekers.
According to a January 25, 2023 article on Forbes.com, there are several reasons that people have left the labor force, including:
- Increased dependent care needs.
- Fear of getting COVID.
- Higher unemployment benefits.
- Desire for higher wages reducing interest in low-paying jobs.
- Higher pace of retirements due to an aging population.
- Slower population growth.
State-by-State Unemployment Rates
Employment rates for the states (excluding territories and districts) range from a low of 1.9% in South Dakota to a high of 5.4% in Nevada. The median unemployment rate is 3.1%.
Source illustration not reproduced.
Even if you live in Nevada, California, Washington, Delaware, or Illinois, those with the five highest, unemployment rates are low.
What Should You Do?
What does this mean for your prospects of finding a job or getting a better one than you have now? Some of these factors, such as the higher pace of retirements and slower population growth, are trends that will benefit employees for the long-term. Others, such as the fear of COVID and the impact of higher unemployment benefits will continue to fade, potentially bringing some, though not all the one million sidelined workers back into the job-hunt.
Inflation and desire for higher wages will continue to push salaries higher.
All of this despite concerns for a recession later this year. If you don’t like what you do or want to make more money, you have a basic decision to make:
Take advantage of the tight employment market to improve your job satisfaction and finances.
or
Let fear of losing a new job because of an economic downturn prevent you from bettering your situation.
The prevailing thinking appears to be if we enter a recession, it will be mild. Do you agree? Is your current job any more secure than a new one would be? Is job security the most important factor to you?
If your answers are yes, no, and no, then now is an outstanding time to job-hunt.
Carpe Futurum Financial
The longer you wait to set and begin working toward your financial objectives, the harder it will be to meet them. Even with higher interest rates, a simple principle shows this is true. It’s the rule of 72, which states that if you divide 72 by the return you receive on an investment, you’ll get the number of years it will take to double your money.
With CD rates at around 5%, 72 ÷ 5 = 14.4, meaning it will take over 14 years to double your money. So even if you have $100,000 to invest today, you need 30 years to have a $400,000 nest egg. Can you meet your financial goals with $400,000 in 30 years?
Now is the time to seize your financial future.
- Start with your income earning situation. Should you look for a better job? Should you start a business?
- Build your rainy-day fund.
- Pay off your debts, home mortgage excluded.
- Start investing money.
Where are you on this journey? Have you set your financial goals?
How can I help you? Call, text, or email me.
Kevin
P.S. Don’t miss this week’s episodes of The WAY to WOW Shows:
Monday, June 5, 10:00 a.m. PT / 1:00 p.m. ET – Trusts & Estate Weekly, guest Cheryl Munk
Tuesday, June 6, 11:00 a.m. PT / 2:00 p.m. ET – Business Lessons from the Military, https://www.eventbrite.com/e/633485551337
Wednesday, June 7, 12:30 p.m. PT / 3:30 p.m. ET – People Making Money, https://www.eventbrite.com/e/633497958447
Process
Time limit: 70 minutes
Create an outline
Write, do not edit
Edit
Add graphics, links, metadata, and referral to other blogs
Read it twice
Read it out loud once
Write a catchy headline - The job of the headline is to get the first line of your copy read
Publish it as a draft and read it on the blog
Publish it
Run post through Scribe on the WordPress admin panel
Style
Write to one person
Up to 500 words per post
Short sentences – avoid compound sentences
Three to four sentences per paragraph
Number headings
Use simple words
Provide links to previous posts that develop a thought in more detail
Question 1: Is this the best thing that’s ever been written on this subject?
Question 2: Does the article make a bold promise and fulfill it?
Question 3: Is this article shareable? (Are their share links and click to tweets? Do you have memorable phrases that are easy to repeat and share?)